When receiving a refund from a supplier, funds must be receipted to the Clearing Property and journalled to the property using an Accounts Payable Transfer Journal. The purpose of the journal is to move the funds back (credit) into the property and reduce the expense code that the funds were originally paid from (debit).
Please note that refunds should not be receipted directly to the property as the goal is to reduce the relevant expense, rather than increase the property income.
Process a refund from a creditor/supplier
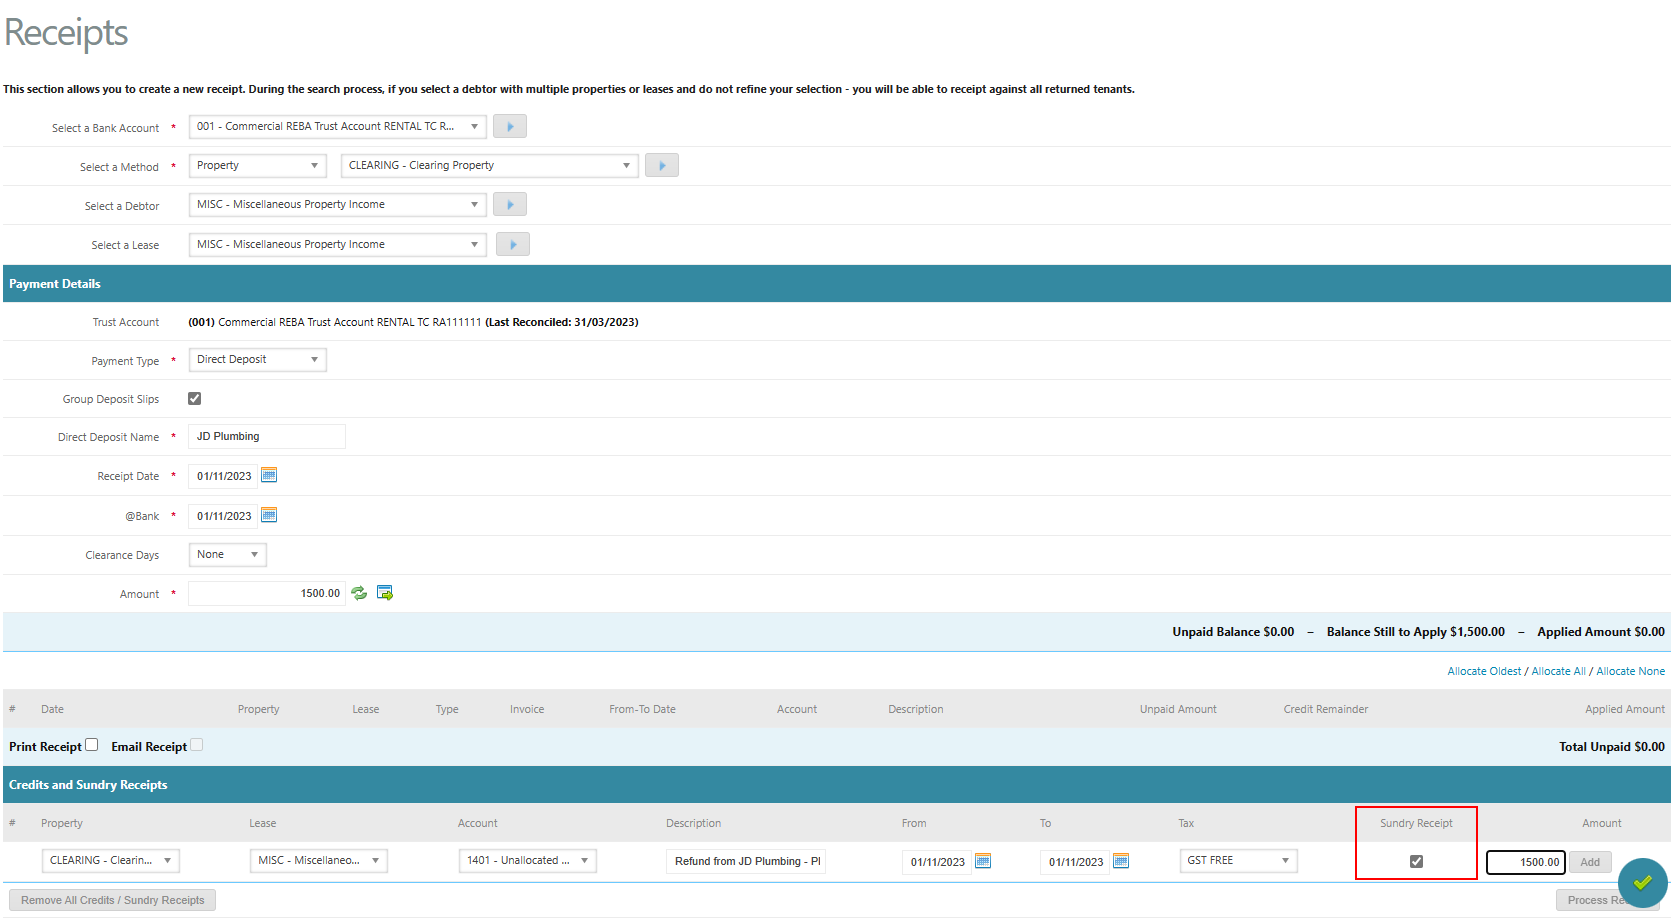
Step 1. Receipt Refund Funds
- Go to Accounts Receivable > Receipts
- Property: Clearing Property
- Lease/Debtor: MISC
- Direct Deposit Name, Date and Amount: as per bank statement
- Click on Add Credit / Sundry Receipt
- Add receipt details
- Tick Sundry Receipt (IMPORTANT - Please refer to this article if you miss this step: Amount In Credit / Sundry Receipts
- Enter Amount, click Add and Process Receipt
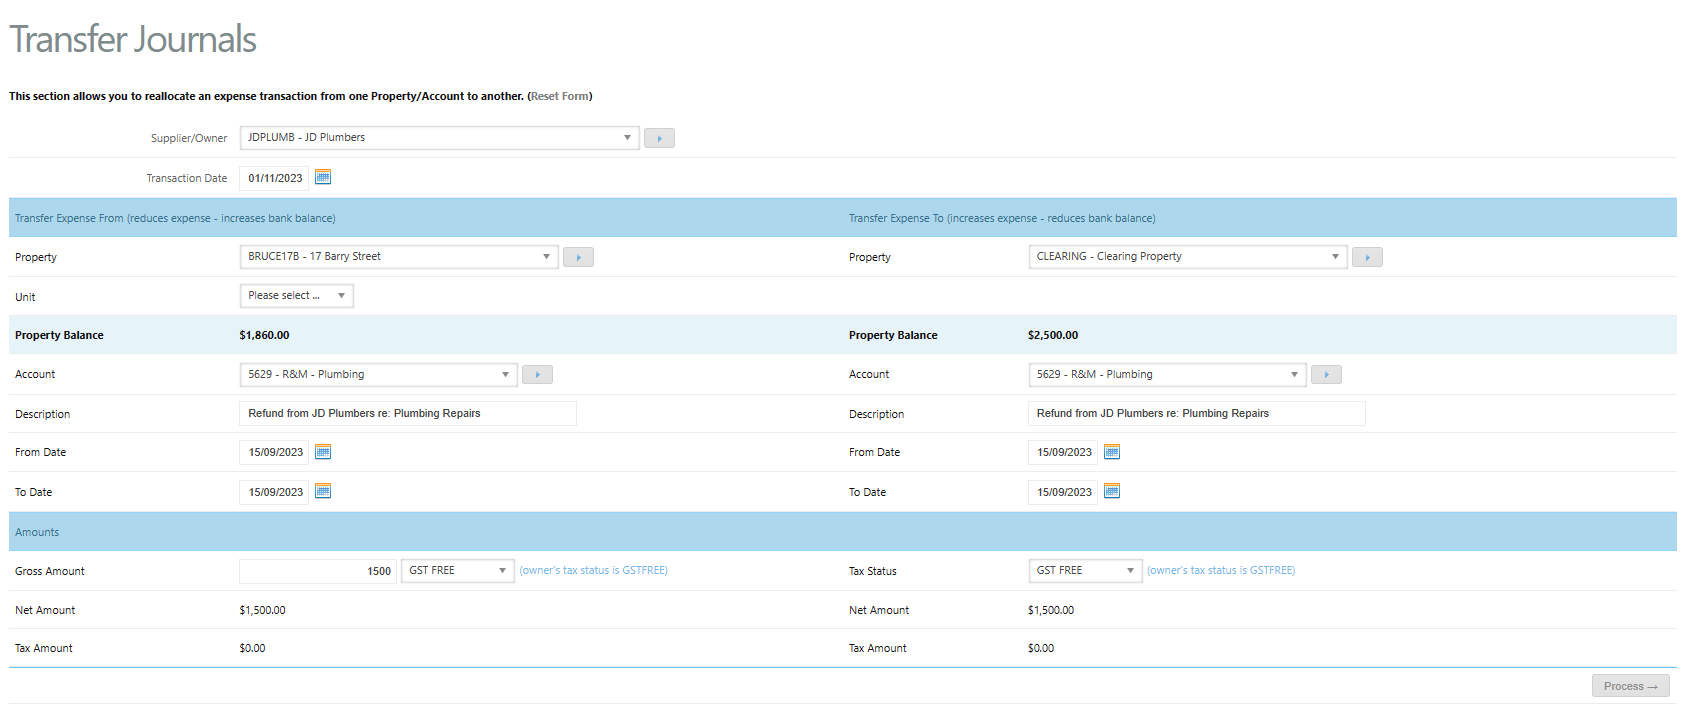
Step 2. Process Accounts Payable Transfer Journal
- Go to Accounts Payable >Transfer Journal
- Supplier - select the creditor you received the refund from.
- Transaction Date - as per date funds received
- Transfer Expense From (reduces expense - increases bank balance)
- Property - select the property entitled to the refund
- Account - select the original account code the invoice was allocated to
- Description - enter a description for the transaction e.g. refund from JD Plumbers
- Dates - enter from and to dates as per original expense paid
- Amount - as per refund received
- GST - Select GST Free or GST Taxed, as per the original expense
- Transfer Expense To (increases expense - reduces bank balance)
- Property - select the Clearing property
- Account - select account code (same as above)
- Description - enter a description for the transaction e.g. refund from JD Plumbers (same as above)
- Dates - will automatically populate based on above
- Amount - will automatically populate based on above
- GST - GST Free
- Click Process
Was this article helpful?
That’s Great!
Thank you for your feedback
Sorry! We couldn't be helpful
Thank you for your feedback
Feedback sent
We appreciate your effort and will try to fix the article